Dyscalculia and Money: You're Not Bad at Math, Your Brain Just Works Differently
Published: October 16, 2026 · By Monica Becerra · 7 min read
You're at the register. The total says $23.65, there's a line behind you, and the coins in your hand have stopped meaning anything. You hand over a $50 bill just to make it end. If that moment sounds familiar, it might not be nerves. It might be dyscalculia.
In short: Dyscalculia is a learning difference in how the brain processes numbers, and it affects roughly 3 to 7 percent of people. It has nothing to do with intelligence. With money, it shows up as trouble counting change, estimating totals, and reading percentages, and it often comes with math anxiety. What helps is fewer numbers, rounding, everyday comparisons, and tools that do the math for you, like Finiverse.
What dyscalculia actually is
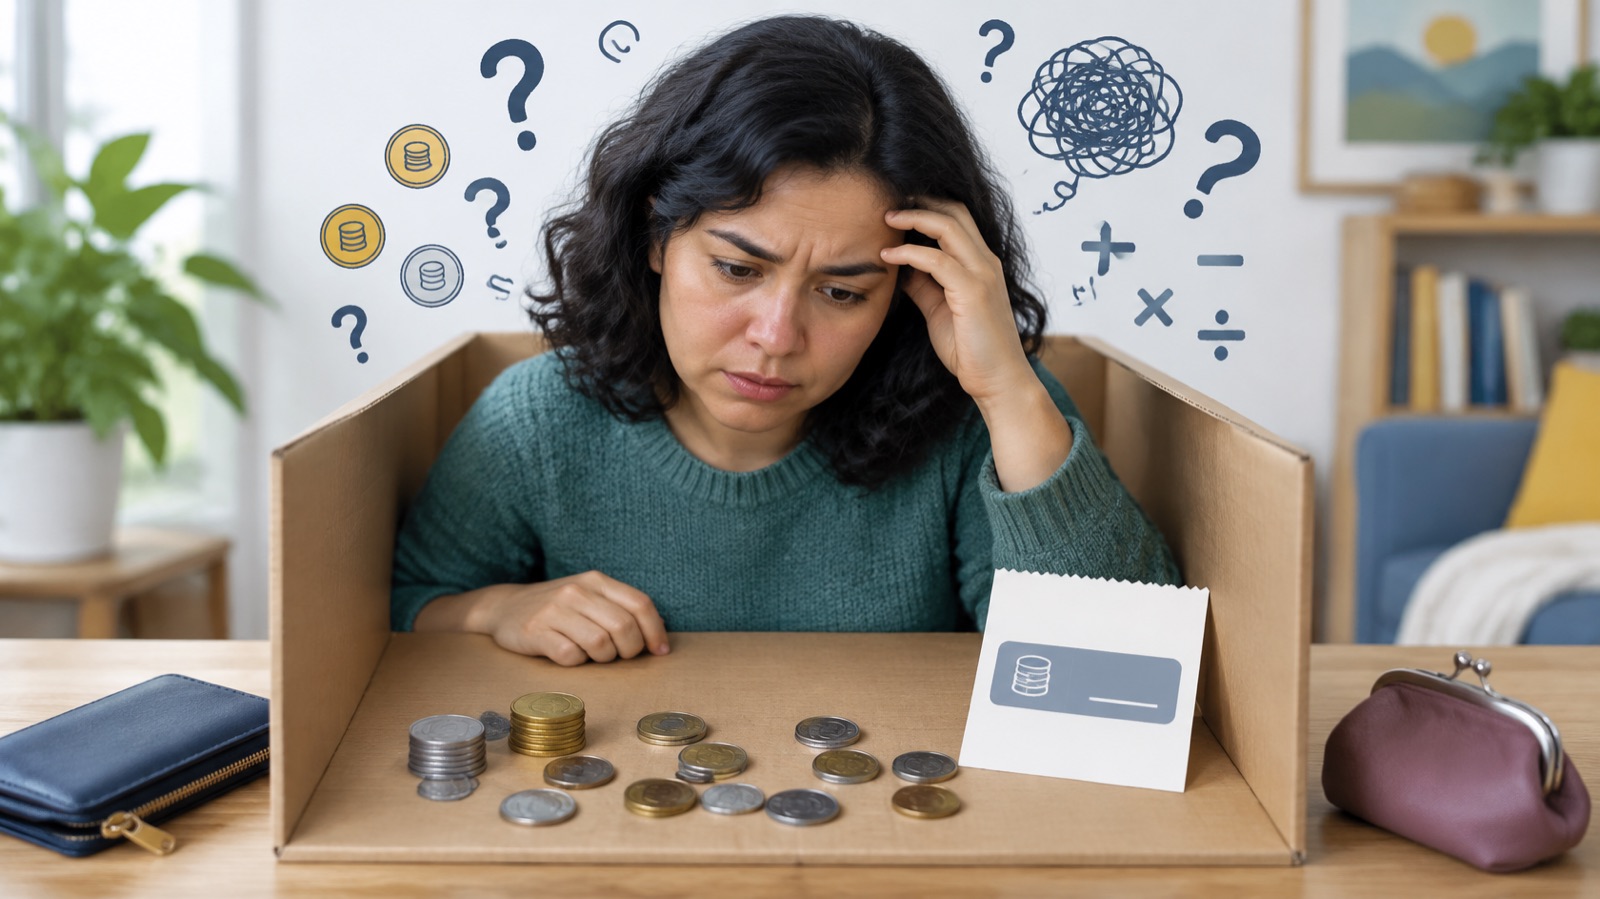
Dyscalculia is a learning difference that affects how the brain understands numbers and quantities. It isn't about being slow, lazy, or not trying hard enough at school. Researchers describe it as a difficulty with number sense itself: the intuitive feel for how big a quantity is, how numbers relate to each other, and what happens when you combine them.
Estimates usually place it somewhere between 3 and 7 percent of people, which makes it roughly as common as dyslexia. Clinically, it falls under specific learning disorder with impairment in mathematics. And yet very few people have heard of it, so many adults go through life without a name for it at all, only a quiet belief that they're “just bad with numbers.”
It has nothing to do with intelligence. Plenty of people with dyscalculia are sharp writers, gifted designers, careful thinkers. Their brains simply don't process numbers the way school, and most financial advice, assumes they will.
Where it shows up with money
Money is numbers all day long, so dyscalculia shows up everywhere. It's counting change while someone waits. It's working out a tip, splitting a dinner bill, or knowing whether the groceries in your cart are closer to $40 or $90 before you reach the register. It's reading a balance like 1,487.32 and not being sure, at a glance, whether that's a lot or a little.
It goes beyond arithmetic, too. Percentages, interest rates, and discounts can feel like a foreign language, which makes comparing a loan or a credit card offer genuinely hard. Due dates mix time and numbers together, and keeping track of which bill is coming when can slip away. A lot of what looks like “careless” money behavior is really a person working twice as hard to manage something that was never designed with them in mind.
The anxiety on top of it
After years of feeling lost around numbers, many people develop math anxiety, a real tension and dread that shows up the moment numbers appear. Research has found that this anxiety takes up working memory, the same mental space you need to do the calculation, so the fear itself makes the math harder.
With money, that becomes a loop. Numbers feel bad, so you avoid looking at them. Avoiding them means bills get missed and balances become a surprise, which makes the numbers feel even worse next time. Most financial literacy programs assume a baseline of comfort with numbers, so the standard fix, “just learn to budget,” often adds to the shame instead of breaking the loop.
Seeing money instead of counting it
Managing money well doesn't require becoming good at mental math. It requires tools and habits that do the math for you, so your energy can go into the decisions.
Fewer numbers help more than better numbers. One clear figure, like how much you can safely spend until payday, is easier to act on than a screen full of balances, pending charges, and percentages. Rounding helps too. $24 is easier to hold in your head than $23.65, and dropping the “.00” on whole amounts removes noise you never needed.
Comparisons make quantities feel real. “That's about three lunches” or “you're halfway to your goal” carries meaning in a way a raw number sometimes doesn't. Words can replace percentages entirely: “the bigger bottle is cheaper per use” tells you what you need to know without asking you to divide anything.
Cash can be planned ahead. If counting change in the moment is stressful, deciding at home which bills to bring, or simply paying with one larger bill, takes the pressure off at the register. Paying by card with instant notifications can help too, since the app keeps the totals for you. And if you use color to make sense of money, green for fine and red for careful, make sure the meaning never depends on color alone. Words and icons keep things clear on a tired day, and for people who see color differently.
How Finiverse is built for this
Finiverse treats dyscalculia as a design requirement, not an edge case. Home leads with one calm number, what's safe to spend after bills and savings, instead of asking you to piece it together yourself. Whole amounts drop the “.00”, and your records always show the total for the period, so you never have to add things up in your head.
Sam, the AI built into Finiverse, does the calculations before answering and explains amounts with everyday comparisons instead of formulas. If you want to know what something really costs you, Finiverse can show prices in coffees or in hours of work. You only enter your monthly pay and your usual weekly hours, and the app does the division. There's also a step-by-step guide for paying in cash: you enter the price, and it shows you which bills and coins to hand over and what change to expect, one step at a time, with the number printed on every bill and coin and the option to hear each step out loud.
None of this makes numbers disappear. It just stops them from being a test you have to pass before you're allowed to understand your own money.
Quick answers
What is dyscalculia?
Dyscalculia is a specific learning difference that affects number sense, the intuitive understanding of quantities and how numbers relate to each other. Clinically it is classified as a specific learning disorder with impairment in mathematics. It isn't related to intelligence or effort.
How common is dyscalculia?
Studies estimate that about 3 to 7 percent of people have dyscalculia, roughly as many as have dyslexia, although it is diagnosed far less often.
How does dyscalculia affect managing money?
It can make it hard to count change, work out tips, split bills, estimate a shopping total, judge whether a balance is large or small, and compare interest rates or discounts. Many people also develop math anxiety, which can lead to avoiding banking apps and bills.
Is there a budgeting app for people with dyscalculia?
Finiverse is a personal finance app built for neurodivergent people, including people with dyscalculia. It shows one safe-to-spend number, drops unnecessary decimals, keeps totals visible, can show prices in coffees or hours of work, includes a step-by-step guide for paying in cash, and has Sam, an AI assistant that does the calculations and explains money in plain words. It's free to download on the App Store.
Sources
- American Psychiatric Association. (2013). Diagnostic and Statistical Manual of Mental Disorders (5th ed.). Specific learning disorder, with impairment in mathematics.
- Butterworth, B., Varma, S., & Laurillard, D. (2011). Dyscalculia: From brain to education. Science, 332(6033), 1049–1053.
- Shalev, R. S. (2004). Developmental dyscalculia. Journal of Child Neurology, 19(10), 765–771.
- Ashcraft, M. H. (2002). Math anxiety: Personal, educational, and cognitive consequences. Current Directions in Psychological Science, 11(5), 181–185.
- Lusardi, A., & Mitchell, O. S. (2014). The economic importance of financial literacy: Theory and evidence. Journal of Economic Literature, 52(1), 5–44.
Money that makes sense without the mental math.
Finiverse does the calculating so you can focus on deciding. One calm number, plain words, no math homework.
Download Finiverse free →